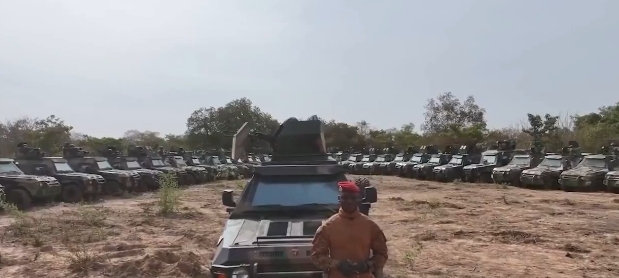
Since captain Ibrahim Traoré came to power, a particular account of events has gradually established itself in official communication: a Burkina Faso that has supposedly taken back control of its own fate, cut down its external dependence and chosen to fund its campaign against armed groups from its own pocket.
The message carries clear political weight. Rearmament is presented as sovereignty turned into something concrete. Military acquisitions are put forward, the patriotic support fund is portrayed as the expression of a nationwide effort, and calls for citizen contributions serve to show that the country would look first to its own resources.
Yet a far less ideological question remains open: how much does this sovereignty really cost, and who ultimately bears the bill?
Defence spending: a change of scale
Budgetary figures already make the shift in magnitude measurable.
Defence and security spending, which hovered around 95 billion CFA francs in 2016, has risen into the hundreds of billions and passed the 800 billion mark in 2024, depending on the budgetary perimeter used.
The rise is considerable. It reflects an unmistakable political priority: in a country grappling with a major security crisis, the state now devotes a much larger portion of its resources to the army, the security forces, equipment and the war effort.
Such a spectacular increase, however, cannot be examined through a purely military lens. Every extra billion channelled into security is also a billion that has to be found somewhere else.
And it is precisely there that the rhetoric of sovereignty deserves to be confronted with the mechanics of public finance.
The patriotic fund: real mobilisation, partial coverage
The patriotic support fund stands out as one of the main symbols of this strategy.
Contributions have reached significant sums since it was launched: close to 99 billion CFA francs during its first year, roughly 175 billion in 2024 and more than 200 billion according to the figures released for 2025.
It would therefore be unfair to deny the scale of the national mobilisation behind it.
But another illusion should be avoided too: the fund does not, by itself, represent the whole of the financing behind the war effort.
Tax revenue, ordinary resources and borrowing
The state budget remains the main structure through which public policy is financed. Military expenditure is therefore also supplied by tax receipts, the state’s ordinary resources and, whenever revenue falls short, by recourse to borrowing.
Put differently, contributing voluntarily to the war effort does not mean the war is being financed without debt.
Public debt has changed its face
This is where the debate becomes more interesting.
Burkina Faso’s public debt has grown sharply since 2021. It now exceeds 8,000 billion CFA francs, based on the data and projections available for recent years.
A significant share of that debt is now raised on the UEMOA regional market, notably through the issuance of public securities.
This allows Burkina Faso to diversify its funding sources and to reduce certain dependencies on external creditors.
Yet a debt contracted on the regional market remains a debt. Whether it is held by a bank, an institutional investor or another financial player in the region does not alter its economic nature: the state borrows today and will have to repay tomorrow, with interest.
This is where communication about sovereignty reaches its limits.
One may perfectly well defend the choice of favouring domestic financing, and equally consider that borrowing from the regional market is preferable to certain forms of external dependency.
But presenting that mechanism as the disappearance of financial dependency would be misleading.
The quiet burden of debt servicing
There is also a less spectacular but far more durable risk: the servicing of the debt.
Every loan taken out today creates an obligation for the years that follow. When interest rates are high and investment needs remain heavy, the government must set aside a larger share of its resources to meet repayment deadlines.
The mechanism is straightforward: the more the state borrows, the more of tomorrow’s revenue it must reserve for its creditors.
Indebtedness in itself is not necessarily the problem; every modern state borrows.
The question is rather whether the spending financed by that borrowing generates enough economic and social returns to allow the country to carry the future burden.
With military expenditure, the equation becomes even more delicate: equipment may be indispensable to national security, yet it does not necessarily produce the revenue needed to repay the loan that paid for it.
Competing priorities and invisible trade-offs
The issue, then, is not whether Burkina Faso has the right to rearm. It plainly does.
The issue is to determine what that rearmament costs the public finances as a whole.
When a growing share of resources is directed towards security, the government has to arbitrate between several priorities: defence, education, health, infrastructure, agriculture, social protection and debt repayment.
Such trade-offs are rarely visible in political speeches. Yet they constitute the genuine test of economic sovereignty.
A state can purchase more weapons while remaining financially vulnerable. It can reduce certain foreign military partnerships while increasing its reliance on borrowing. It can mobilise patriotic contributions while devoting a growing portion of its future revenue to servicing debt.
Diplomatic rupture, therefore, does not automatically amount to financial rupture.
The Burkinabè paradox: military autonomy, financial dependency
This is the contradiction the Burkinabè model brings to light.
The authorities claim strategic autonomy: new partners, a diversification of alliances, national mobilisation and a scaling back of certain traditional forms of cooperation.
At the same time, the economy continues to operate with the classic instruments of public financing: taxation, domestic debt, the regional market, multilateral creditors and economic cooperation.
None of this is an exceptional contradiction. It is the ordinary functioning of a state with limited resources and enormous security needs.
The difficulty begins when political communication turns that financial reality into a narrative of absolute self-sufficiency.
Bringing exaggerated claims back to scale
Certain assertions circulating on social networks also need to be set straight.
Speaking of a military debt amounting to “hundreds of billions of dollars” is incompatible with the order of magnitude of Burkina Faso’s economy.
The country’s GDP falls within a range of a few tens of billions of dollars, not hundreds of billions. A military debt of several hundred billion dollars would vastly exceed the country’s economic capacity.
Reality is already serious enough that it needs no exaggeration. What is at stake is hundreds of billions of CFA francs, not hundreds of billions of dollars.
That distinction is essential to any serious analysis.
What sovereignty should truly be measured by
Burkina Faso may therefore legitimately claim political and military sovereignty while remaining an indebted state.
But that reality forces a more demanding question: how far can the financing of the war go without weakening the state’s other functions?
Sovereignty is not measured only by the number of armoured vehicles, drones or weapons acquired.
It is also measured by the ability to pay civil servants, to invest in education and health, to finance infrastructure, to support a productive economy and, above all, to repay the loans contracted in the name of the community.
The point is not to deny the efforts made by the Burkinabè authorities. It is to look behind the narrative.
Who pays? How much? With which resources? And for how long?
If a substantial part of the rearmament rests on public revenue, national contributions and borrowing, then the sovereignty being proclaimed is not a sovereignty without cost.
It is a sovereignty financed by taxpayers, savers, financial markets and future generations.
That is precisely why “sovereignty on credit” deserves to be posed as a question rather than repeated as a slogan.
Political independence can be declared in a few speeches. Financial independence is verified in the accounts.
You may also like
Texforces-BF: a textile plant built on Burkina Faso’s retirement savings
Niger’s external liabilities reach 12,900 billion CFA francs as dependence deepens
Benin’s school canteens now feed 1.9 million children every school day
Sifi Grine in Bamako: Assimi Goïta’s junta swallows its pride before Algiers
Inside Mali’s worst military setback: the fall of the Dioura camp to JNIM